
Why choose between stability and flexibility when you can have both? A Split Home Loan allows you to divide your loan into fixed and variable portions. This strategy helps balance protection from interest rate increases while maintaining repayment flexibility.
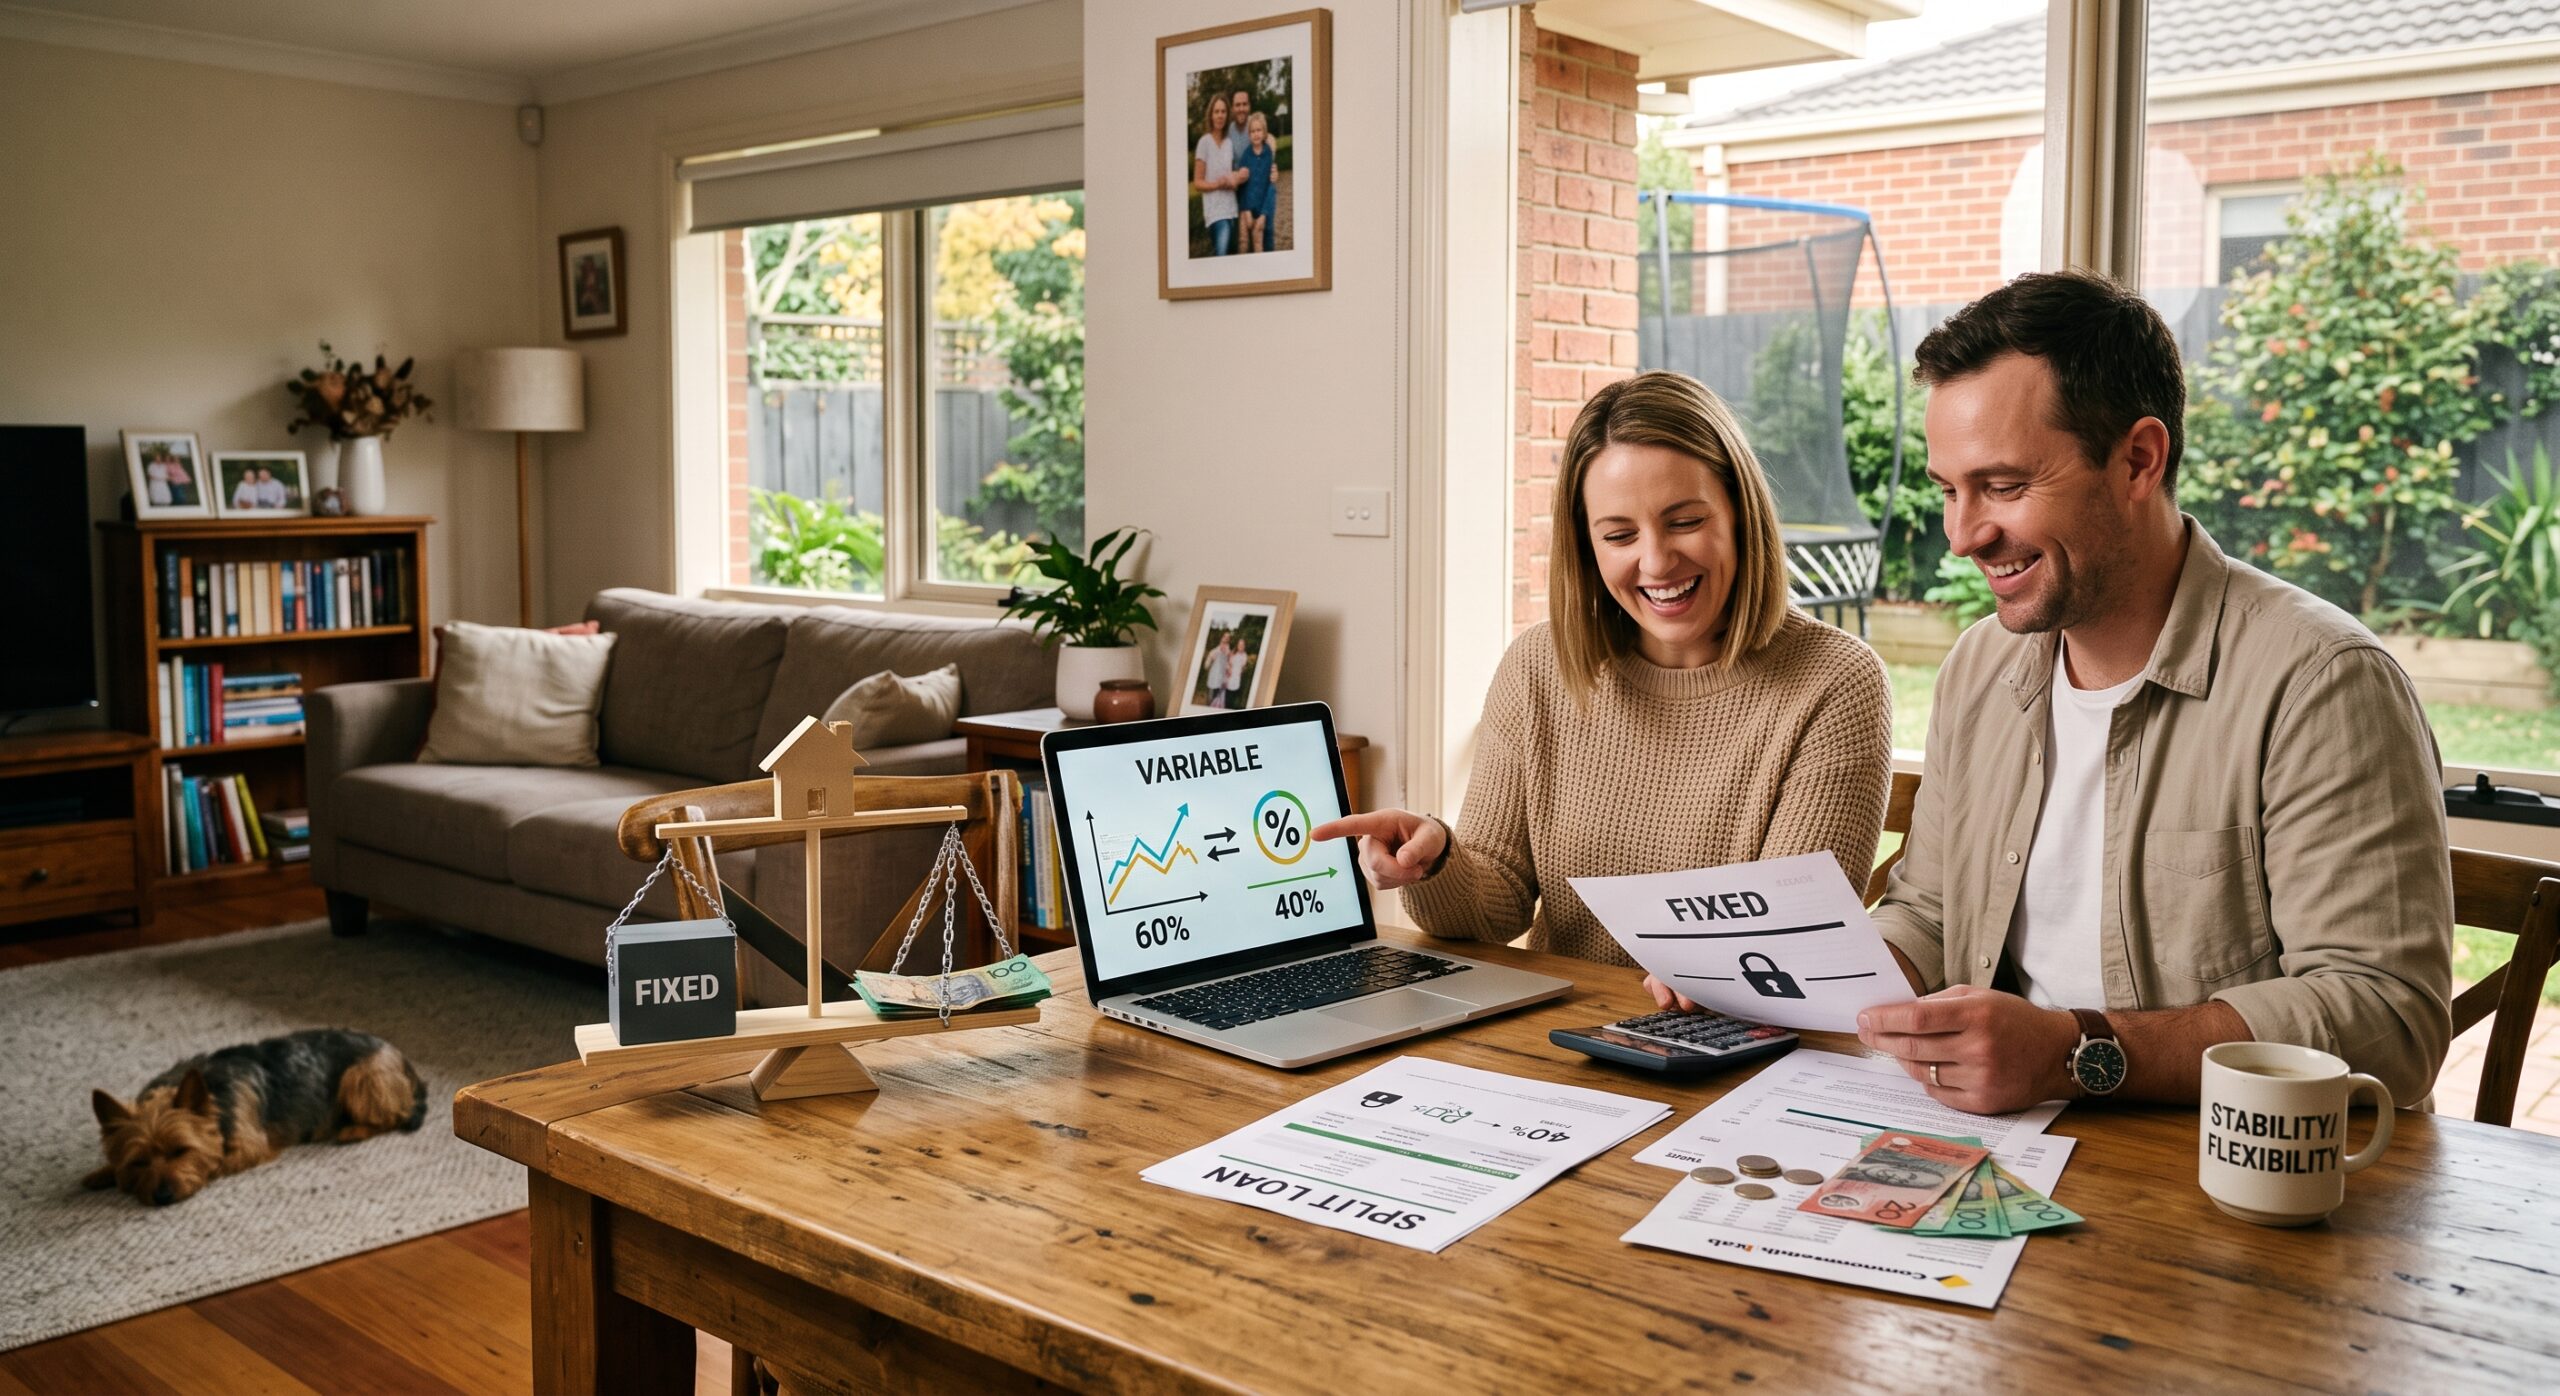
Part of your loan is locked into a fixed rate for repayment certainty, while the remaining portion stays variable, giving you access to features like offset accounts and extra repayments.
A balanced loan strategy can help reduce exposure to rate increases while keeping flexibility. Adjust your approach as market conditions change, with stability on part of your loan and flexibility on the rest.
A balanced loan strategy can help reduce exposure to rate increases while keeping flexibility. Adjust your approach as market conditions change, with stability on part of your loan and flexibility on the rest.
If you plan to keep savings in an offset account, make sure the variable part of your loan is at least as big as the savings you expect to hold.
Most of the loan is protected from rate rises, with a small variable part for an offset buffer. This may suit households on a tight budget.
Half the loan is protected from rate rises, and the other half gives you room to pay your loan down faster. A popular middle ground.
Most of the loan stays flexible for large extra repayments, for example from a bonus or inheritance, with a small part fixed just in case.
A split loan is usually set up as two separate loan accounts, so some lenders charge two sets of monthly fees or application fees. Many package loans cover several splits under one annual fee. We'll check how fees apply before you choose a loan.
If you want to move to a different lender later, the fixed part can make it harder. You may need to wait for the fixed term to end, or pay break costs to move the whole loan. That's why it's worth matching your fixed term to your plans. For example, if you're likely to sell in 2 years, a 5-year fixed term probably isn't the right fit.
When the fixed term ends, that part of your loan usually rolls onto a variable rate, often the lender's standard variable rate, which can be higher than rates offered to new customers. We can review both parts of your loan before then and ask your lender for a more competitive rate.
We look at your income, lifestyle and how comfortable you are with rate changes, then help you choose a split structure that suits your situation.
If you might sell, refinance or make a large extra repayment in the next few years, a shorter fixed term or a smaller fixed part can help you avoid break costs.
Most lenders allow you to fix a portion of a variable loan at any time. However, changing an existing fixed portion back to variable usually triggers "break costs." It is best to set your ratio based on your 1- to 5-year outlook.
Yes, most Australian banks require a minimum balance for each account—often around $10,000 to $20,000. You can’t split a tiny amount just to get a feature; both portions must meet the lender's threshold.
No. This is a common misconception. An offset account only reduces the interest on the variable portion of your split loan. This is why many borrowers keep enough in the variable side to match their expected savings.No. This is a common misconception. An offset account only reduces the interest on the variable portion of your split loan. This is why many borrowers keep enough in the variable side to match their expected savings.
It depends on your loan package. Some "no-fee" basic loans might charge a small fee for each sub-account, while "Premium Packages" usually cover multiple split accounts under one annual fee.
You can sell at any time, but you will likely incur break costs on the fixed portion of the loan. The variable portion can usually be paid out without those specific penalties.
Yes! Some lenders allow you to divide your loan into up to 6 different portions. This is popular for investors who want to fix different amounts for different lengths of time (e.g., 20% for 2 years, 20% for 5 years, and 60% variable).
This depends on your "sleep at night" factor. If you are worried about rate hikes, a higher fixed percentage (like 70% or 80%) offers more protection. If you have large savings or a fluctuating income, a higher variable percentage allows you to use your offset account more effectively.
You will receive one statement, but it will show two distinct loan accounts. You’ll have a fixed repayment amount for one part and a variable repayment for the other. These are usually debited as two separate transactions.
Usually, no. If your current loan has a "split facility," your lender can often restructure it internally without a full refinance application, though a small administrative fee may apply.
There is no "better"—only "better for you." A split loan is a hedging strategy. It ensures you aren't 100% exposed to rate rises, but you also aren't 100% locked out of features like unlimited extra repayments.
Book an Consultaiton



Kubaer Finance helps working families and migrants in Adelaide secure home, car, and investment loans with personalised guidance.