
A car loan is money you borrow to buy a vehicle and repay, with interest, over a set term, usually between one and seven years. Most car loans are secured, which means the car is used as security for the loan. Because the lender can take the car back if repayments stop, secured car loans generally have lower interest rates than unsecured personal loans.
We can arrange finance for new cars, demonstrators and used cars, whether you're buying from a dealer or from a private seller. New and near-new cars usually attract the lowest rates. For older cars, many lenders set a maximum age the car can reach by the end of the loan, and some will only offer an unsecured loan once a car passes a certain age. Buying privately can get you a better price, but it carries more risk. Before any money changes hands we check the Personal Property Securities Register (PPSR) to make sure the car has no finance owing and isn't recorded as stolen or written off. Your lender pays the seller directly at settlement, so you're protected and the seller gets paid.
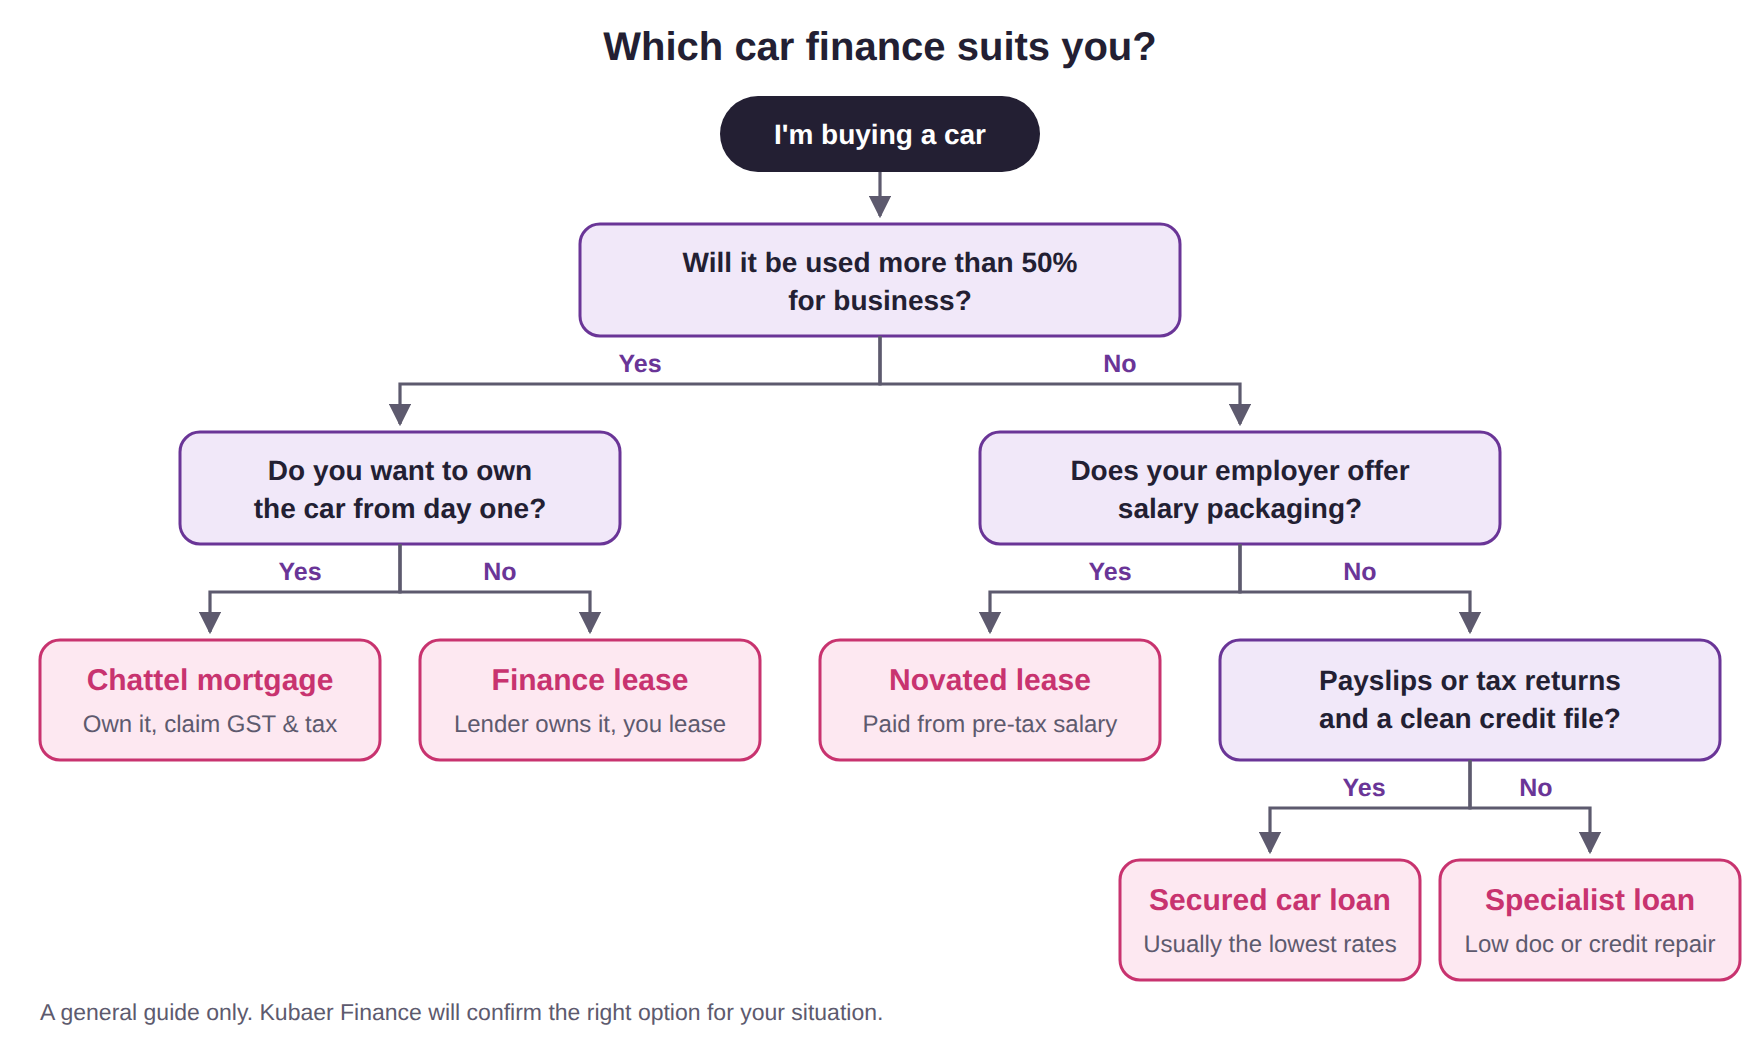
If you use the car for business more than half the time, a chattel mortgage or finance lease is often better value than a personal car loan. With a chattel mortgage you own the car, and if you're registered for GST you can generally claim the GST on the purchase price in your next BAS, up to the ATO limit. You can also claim depreciation and interest for the business-use portion of the car. For the 2026–27 financial year, depreciation on a passenger car is capped at the car limit of $69,883, and the most GST you can claim on a car is $6,353. Small businesses with turnover under $10 million can instantly write off a car that costs less than $20,000. Utes and vans designed to carry a tonne or more are not subject to the car limit. Your accountant can confirm what applies to you.
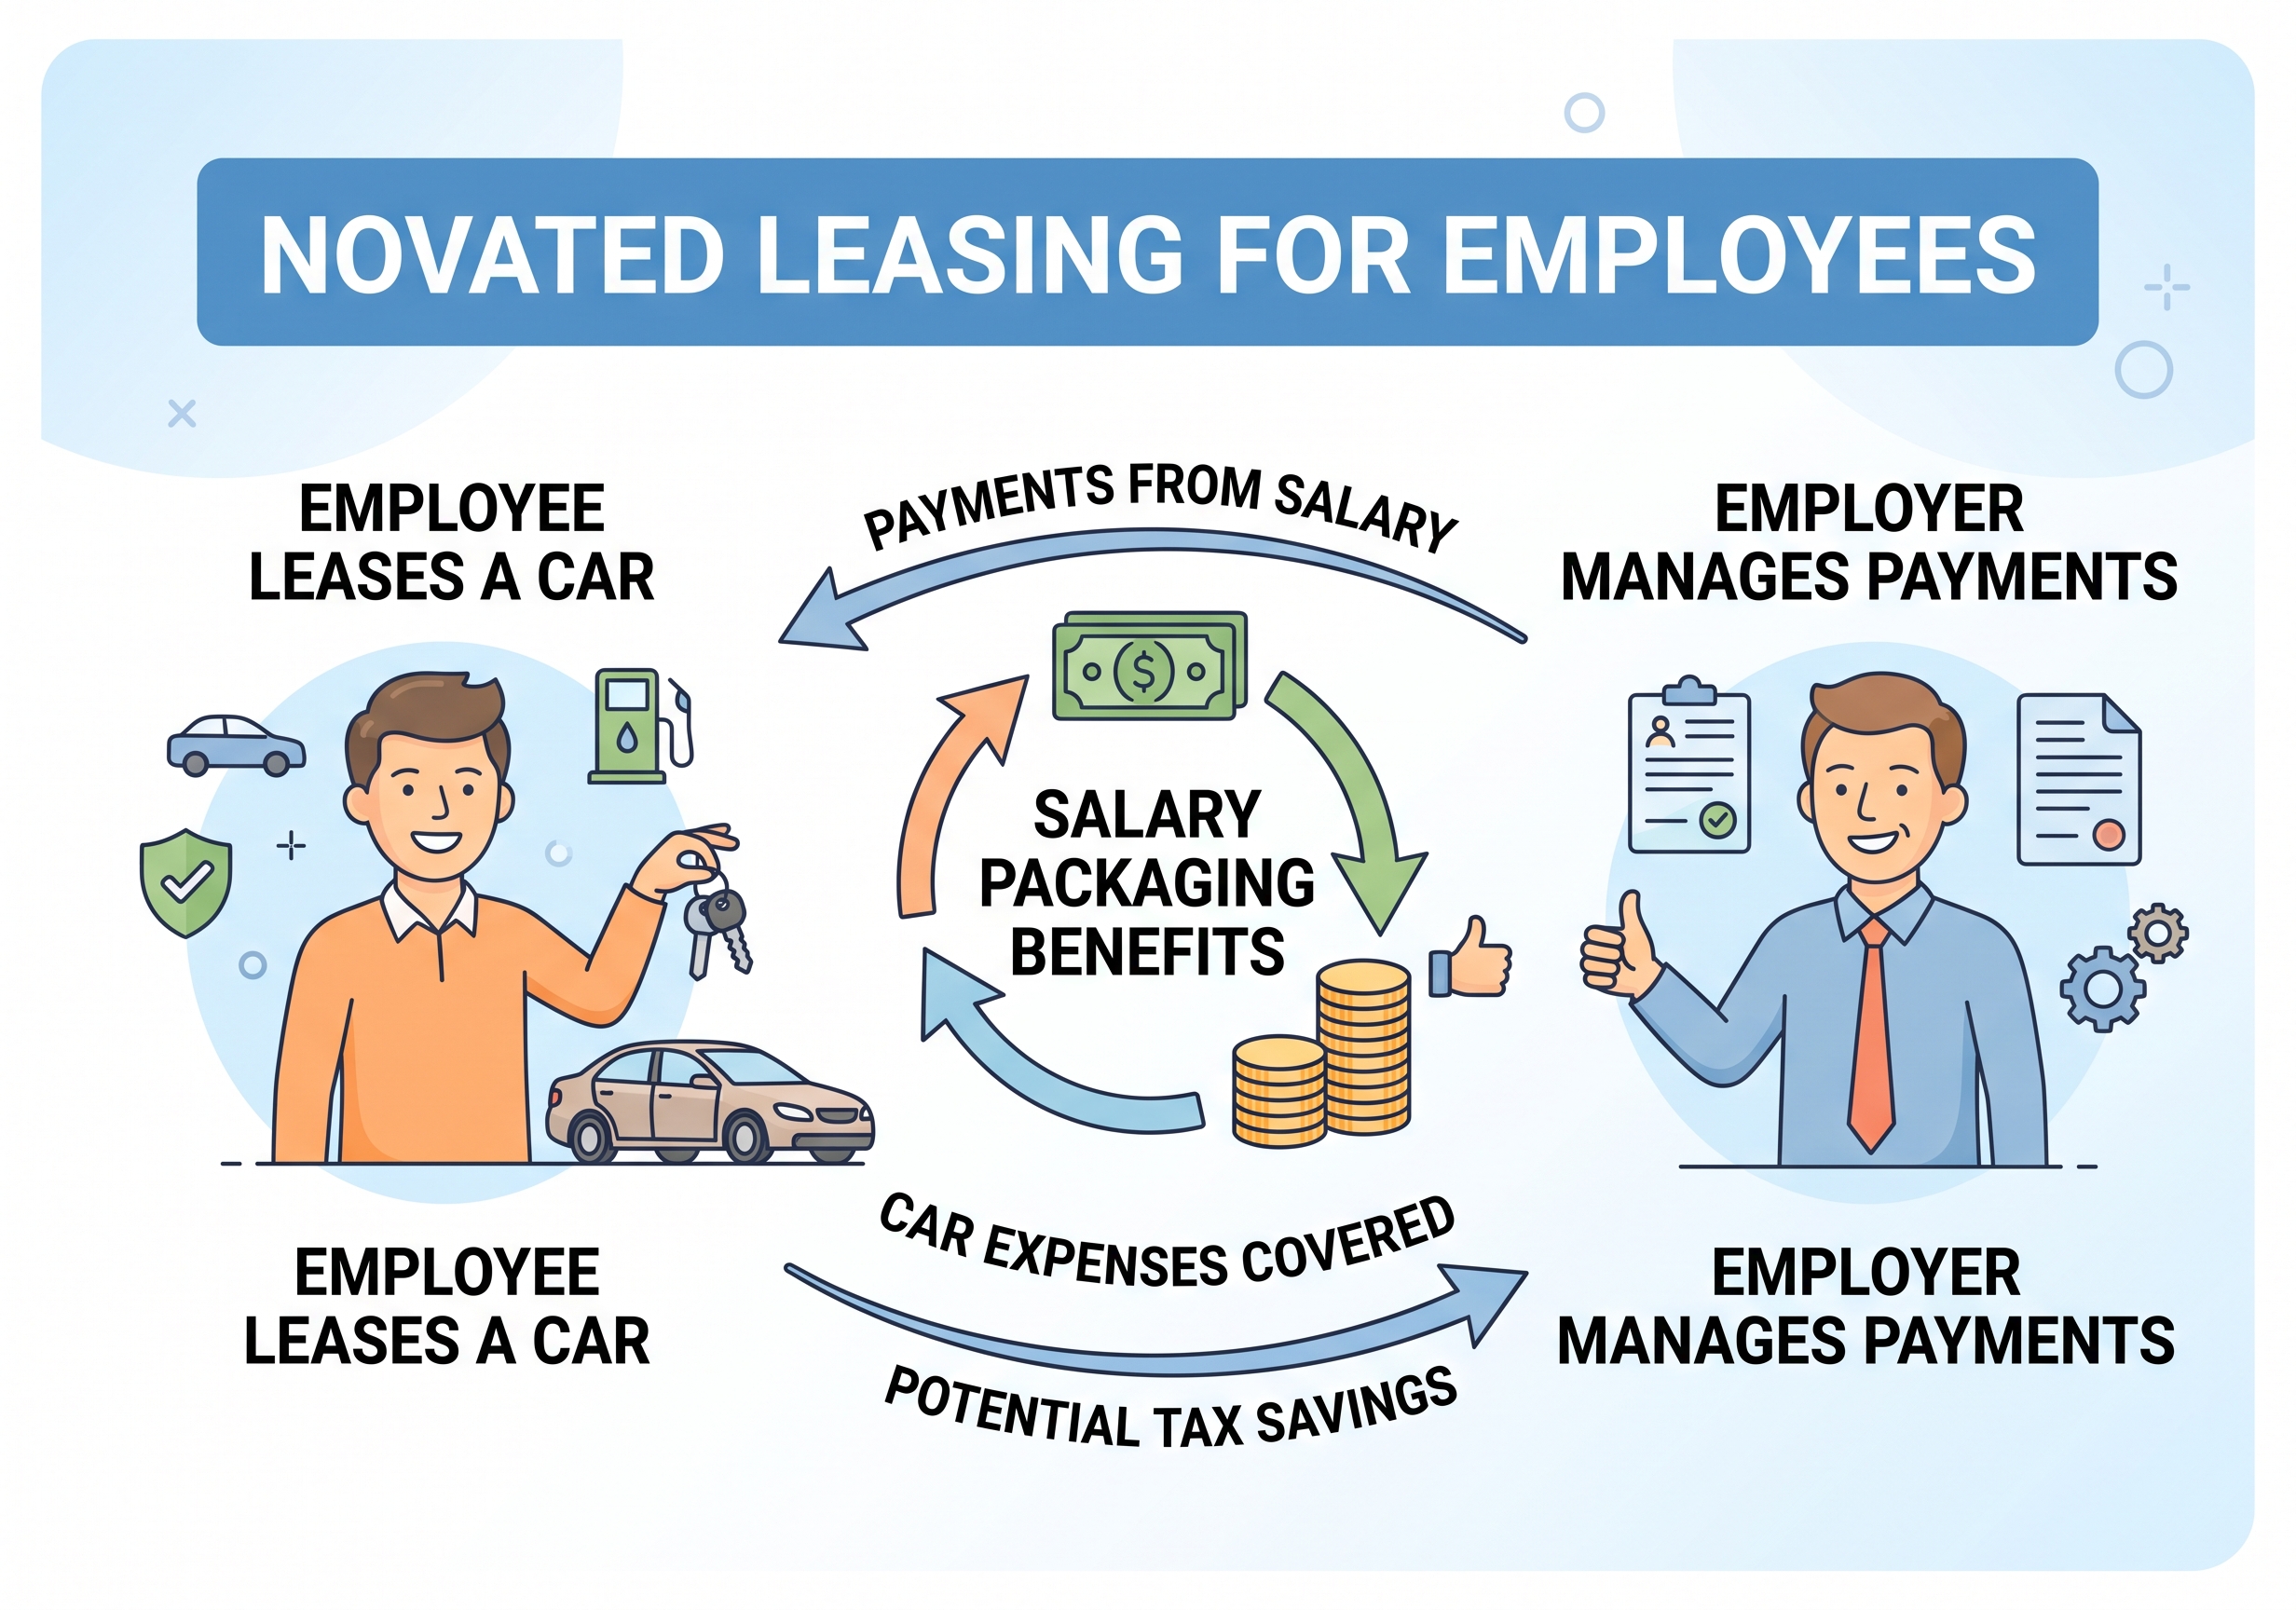
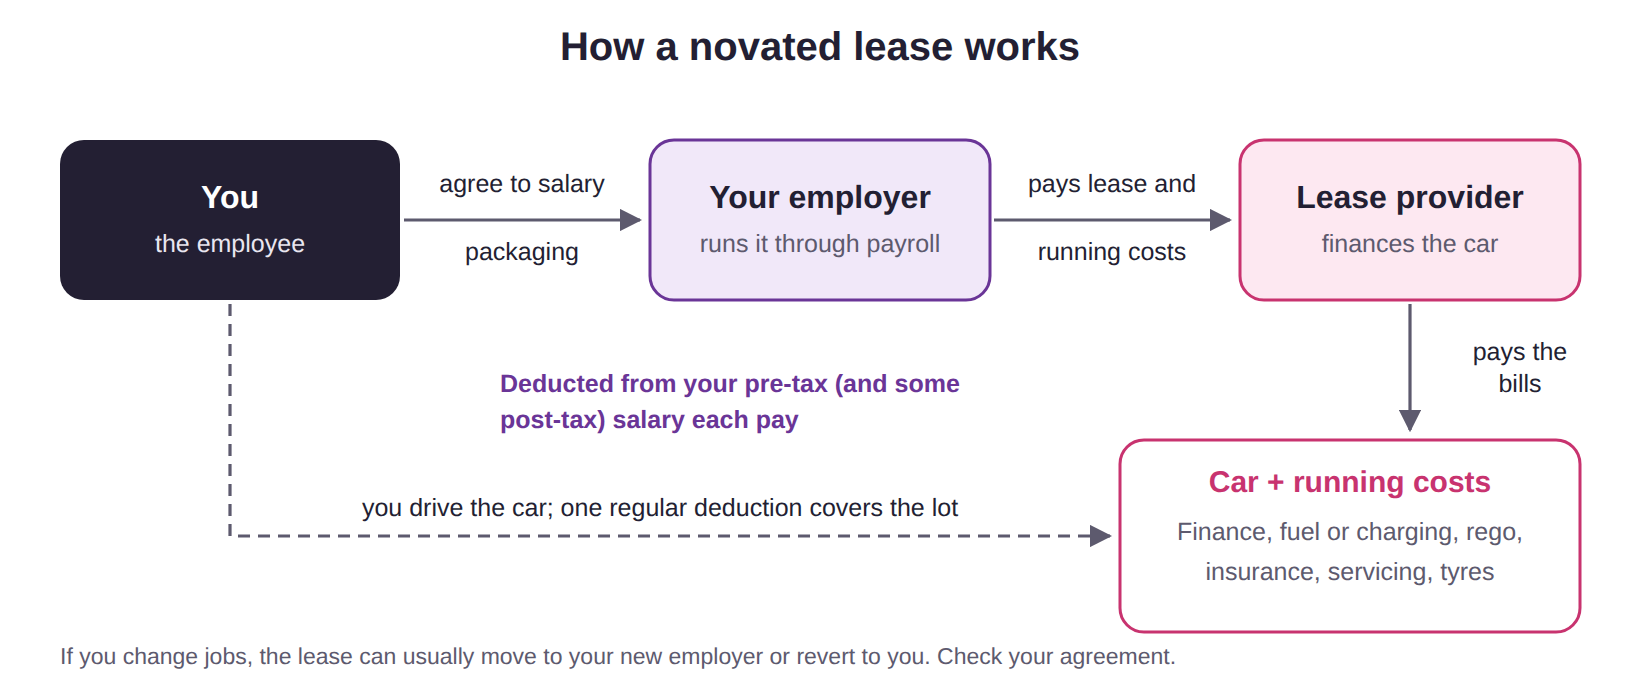
A novated lease lets you pay for a car and its running costs out of your salary. Your employer deducts one regular amount from your pay, partly before tax, and passes it to the lease provider, who pays the finance, fuel or charging, registration, insurance and servicing. Because part of the cost comes from your pre-tax income, you may pay less income tax. At the end of the lease there is a residual value, set by ATO guidelines, which you can pay to keep the car, refinance, or trade in for a new lease. Your employer needs to offer salary packaging for a novated lease to be possible. We'll run the numbers so you can compare a novated lease with a standard car loan side by side.
Many lenders offer lower "green" rates for electric vehicles, and some extend them to hybrids. If you use a novated lease, an eligible battery electric car priced under the luxury car tax threshold for fuel-efficient vehicles ($91,661 in 2026–27) is currently exempt from fringe benefits tax, which can make the savings significant. That exemption is changing. The Government announced in the 2026–27 Budget that from 1 April 2027 the full exemption will apply only to EVs up to $75,000, with a 25% discount above that up to the threshold, and from 1 April 2029 only the 25% discount will remain. Existing arrangements are not affected. Plug-in hybrids stopped qualifying from 1 April 2025 unless the arrangement was already in place.
If you're self-employed and your tax returns aren't up to date, a low doc car loan lets you show your income with BAS statements, business bank statements or an accountant's declaration. Most lenders want an active ABN, and many prefer GST registration and at least 12 months of trading, although some will consider less. If you've had defaults, late payments or a past hardship arrangement, specialist lenders may still be able to help. Rates are higher, so the goal is a loan you can comfortably repay that helps rebuild your credit history, and then refinancing to a better rate later. We'll only apply where you have a good chance of approval, so you don't collect extra credit enquiries.
If you took dealer finance in a hurry, your credit score has improved since you bought the car, or rates have moved, refinancing could cut your repayments or the total interest you pay. A new lender pays out your old loan, and you start making repayments to the new one. Before switching we compare your current loan's payout figure, any early exit fees and the new loan's comparison rate, so you can see whether you'll come out ahead. We also check whether your current loan has a balloon payment coming up, since refinancing can be a way to manage it.
Get pre-approved before you visit the dealer. Knowing your borrowing limit lets you negotiate on the drive-away price, not the monthly repayment. Always compare the comparison rate, which includes most fees, not just the headline interest rate.
tell us your budget, the car you're after and how you'll use it.
send us your ID, proof of income (payslips, or BAS and tax returns), recent bank statements and details of your current debts.
we compare comparison rates, fees, terms and balloon options, and explain the trade-offs.
you know your limit before you start negotiating.
send us the dealer invoice or private sale details. We run a PPSR check on private sales.
the lender pays the seller, you arrange insurance, and you drive away.
| Option | Best for | Who owns the car | Tax & GST | Balloon / residual | Typical term |
|---|---|---|---|---|---|
| Secured car loan | Personal buyers, newer cars | You (lender has security) | No claims for private use | Optional | 1–7 years |
| Unsecured personal loan | Older cars, flexibility | You | No claims for private use | No | 1–7 years |
| Chattel mortgage | Businesses, ABN holders | Your business | GST credit up front; interest and depreciation deductible for business use | Optional | 1–5 years, sometimes 7 |
| Finance lease | Businesses that prefer to lease rather than own | Lender | Lease payments generally deductible for business use; GST on each payment | Yes, residual | 1–5 years |
| Novated lease | Employees with salary packaging | Lease provider during lease | Paid partly from pre-tax salary; FBT rules apply (EV exemption) | Yes, ATO residual | 1–5 years |
| Low doc car loan | Self-employed without recent tax returns | You or your business | Depends on use | Optional | 1–5 years |
| Dealer finance | Convenience, manufacturer offers | You | Depends on use | Often, sometimes with guaranteed future value | 1–5 years |
| Document | Employee (PAYG) | Self-employed, full doc | Self-employed, low doc | Business / company |
|---|---|---|---|---|
| Photo ID (licence, passport) | ✓ | ✓ | ✓ | ✓ directors |
| Recent payslips | ✓ usually 2 | |||
| Tax returns & notices of assessment | Sometimes | ✓ 1–2 years | ✓ business & personal | |
| BAS statements | Sometimes | ✓ recent | ✓ | |
| Bank statements | ✓ 3 months | ✓ | ✓ 6–12 months business | ✓ |
| Accountant’s declaration | Some lenders | |||
| ABN / company details | ✓ | ✓ | ✓ | |
| Car details (invoice or contract) | ✓ | ✓ | ✓ |
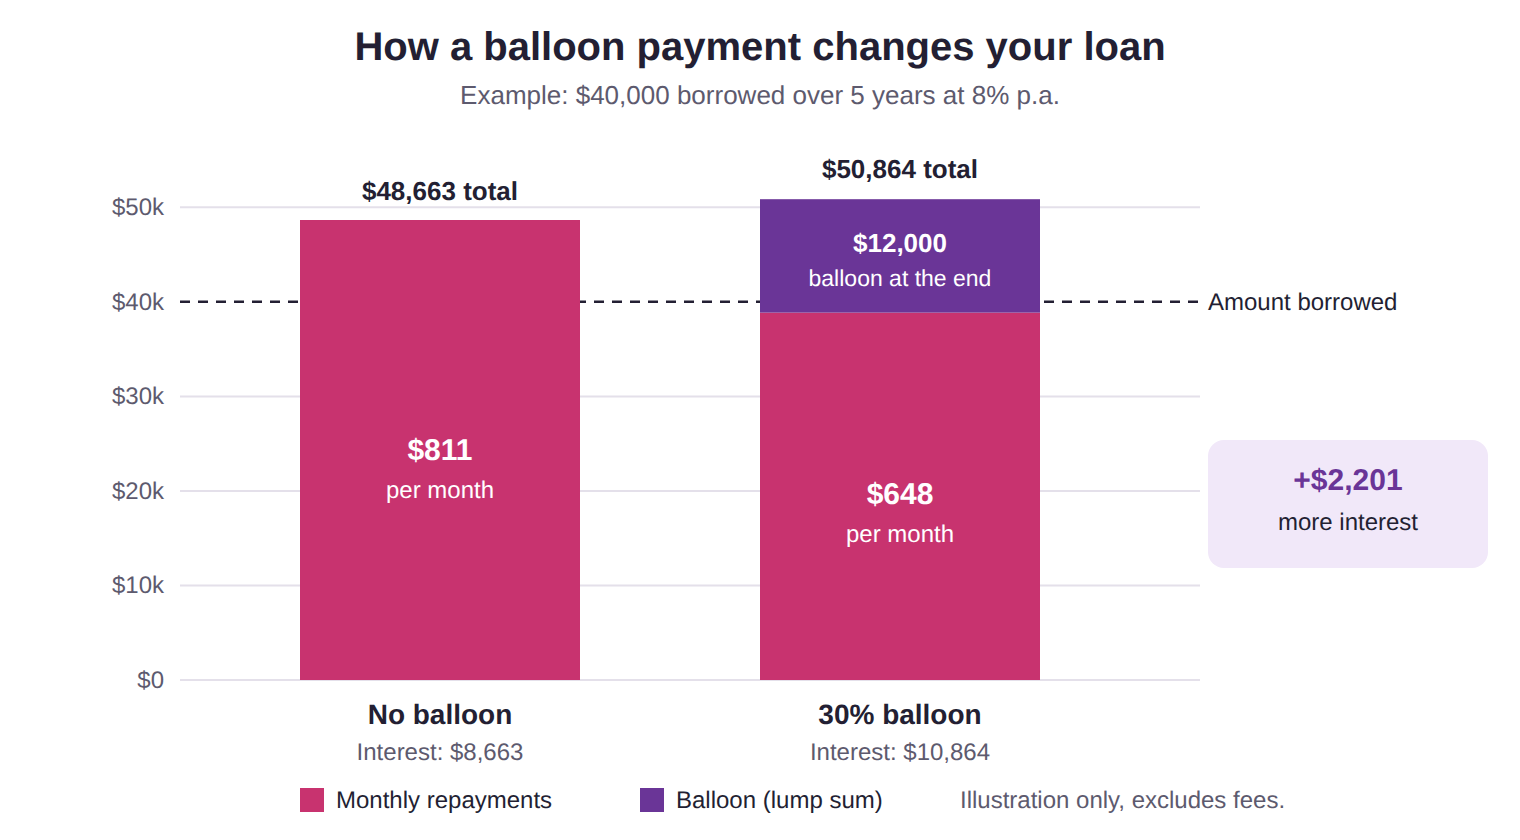
A balloon (or residual) is a lump sum you agree to pay at the end of the loan. It lowers your regular repayments, but you pay more interest overall because you’re paying off less of the loan along the way.
| Lease term | Minimum residual (% of car’s cost) | Example on a $50,000 car |
|---|---|---|
| 1 year | 65.63% | $32,815 |
| 2 years | 56.25% | $28,125 |
| 3 years | 46.88% | $23,440 |
| 4 years | 37.50% | $18,750 |
| 5 years | 28.13% | $14,065 |
| Threshold | 2026–27 amount | What it means |
|---|---|---|
| Car limit | $69,883 | Maximum cost used to work out depreciation on a business car |
| Maximum GST credit | $6,353 | Most GST a registered business can claim on a car |
| LCT threshold, fuel-efficient cars | $91,661 | Luxury car tax (33%) applies above this; also the EV FBT exemption cap |
| LCT threshold, other cars | $80,809 | Luxury car tax (33%) applies above this |
| Instant asset write-off | Under $20,000 | Small businesses (turnover under $10m) can deduct the full cost straight away |
Source: Australian Taxation Office. Thresholds are indexed each financial year.
Finding the right car doesn’t have to be difficult. At Kubaer Finance, we help you source new and used vehicles that match your budget, lifestyle, and preferences. Through our trusted dealer network, we compare options and negotiate competitive prices, saving you time and effort.
Personalised vehicle search
Access to a trusted dealer network
Competitive price negotiation
New and used vehicle sourcing
Car finance arranged in one simple process
Whether you’re buying your first car, upgrading your family vehicle, or purchasing a business vehicle, we’ll help you find the right car and the right finance solution—all in one place.
New Cars
Used Cars
SUVs
Utes
Electric Vehicles (EVs)
Hybrid Vehicles
Family Cars
Luxury Vehicles
Business & Commercial Vehicles
Budget for more than the repayment. Insurance, registration, fuel or charging, servicing and tyres can add hundreds of dollars a month. Lenders include these costs when they assess your application, and so should you. A shorter loan term costs less in total interest if you can afford the higher repayment.
Book an Consultaiton



Kubaer Finance helps working families and migrants in Adelaide secure home, car, and investment loans with personalised guidance.