
First Home Buyer Stamp Duty Exemptions and Concessions. Many first home buyers pay no stamp duty or a reduced amount, thanks to state exemptions and concessions. The rules depend on where you buy, what you buy and whether you'll live in it, so it pays to check before you sign.
A full exemption means you pay $0 stamp duty, usually when the property is under a value threshold, is a new home in some states, and you meet the owner-occupier rules. A partial concession means you pay less, usually on a sliding scale that phases out as the price rises towards an upper cap. Because each state sets its own rules, a home that's fully exempt in one state might only get a partial concession, or none, in another. Some states, like South Australia, focus their relief on new homes and land.
Duty is usually calculated on the dutiable value, which is the higher of the purchase price and market value, using rates that rise as the value rises. It can also depend on whether the property is new, established or vacant land, whether you're an owner-occupier or investor, and whether foreign buyer surcharges apply. Stamp duty is separate from conveyancing fees, loan fees, inspections, registration fees and LMI. It's usually paid at settlement, or within about 30 days, and your conveyancer applies any concession as part of the duty assessment.
| State or territory | Full exemption | Partial concession | Notes |
|---|---|---|---|
| New South Wales | Homes up to $800,000; vacant land up to $350,000 | Homes to $1,000,000; land to $450,000 | New and established homes |
| Victoria | Homes up to $600,000 | To $750,000 | Off-the-plan concession extended to April 2027 |
| Queensland | New homes and vacant land: no value cap; established homes up to $700,000 | Established homes to $800,000 | First home concession |
| Western Australia | Homes up to $600,000; vacant land up to $450,000 | Homes to $800,000; land to $550,000 | From 7 May 2026 |
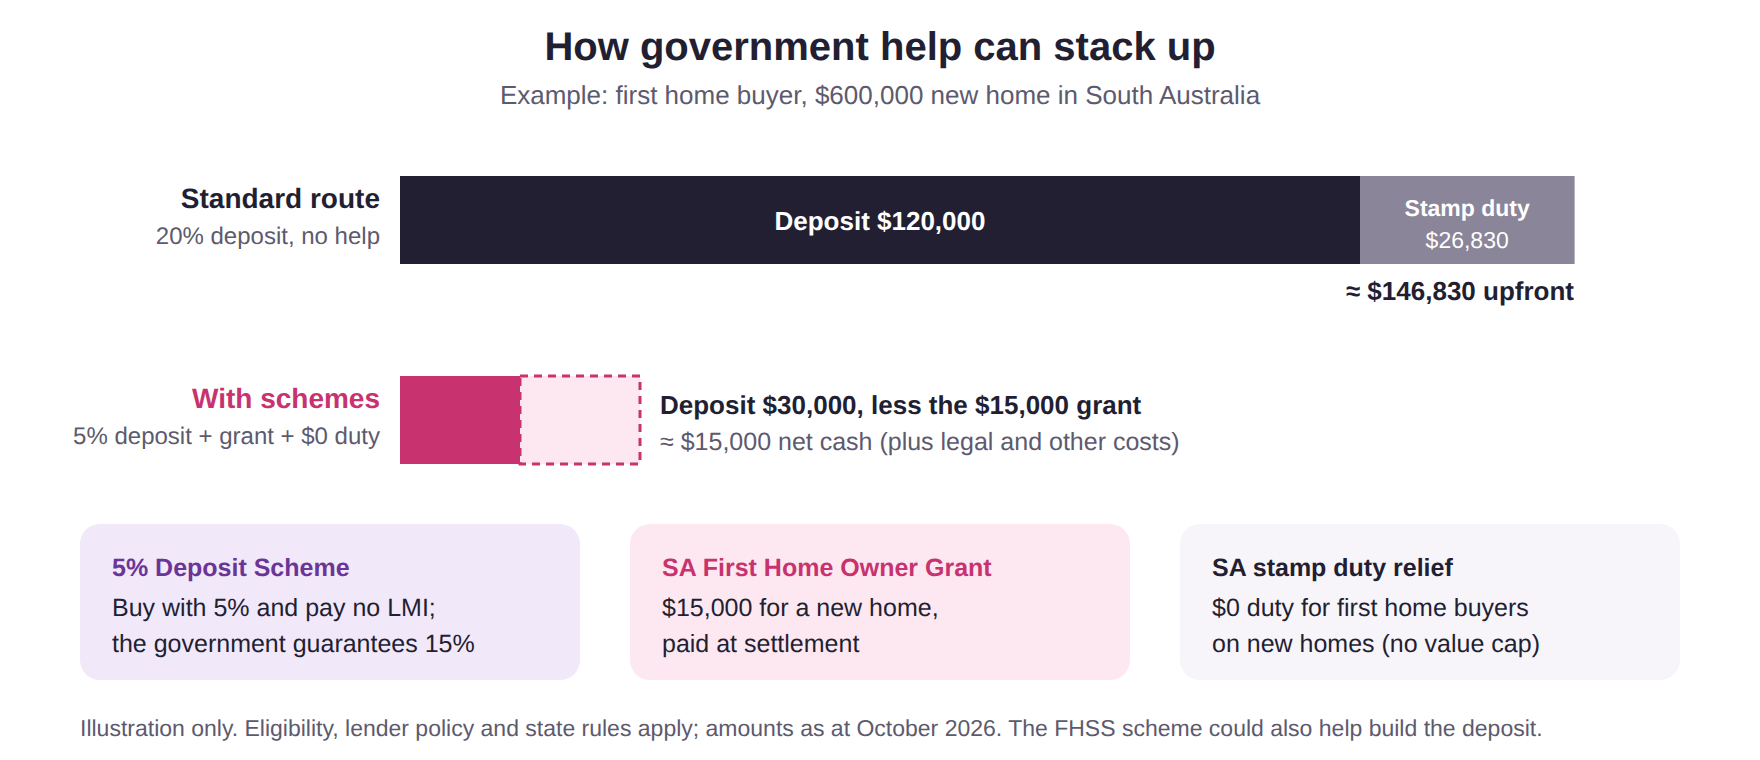
| South Australia | New homes and vacant land: no value cap | Established homes: no first home concession | From 6 June 2024 |
| Tasmania | Exemption ended 30 June 2026 | None for new purchases | Exemption up to $750,000 ended; check current settings |
| ACT | No duty for eligible first home buyers, no income or price cap | n/a | From 1 July 2026, Home Buyer Concession Scheme |
| Northern Territory | Limited; house and land package exemption may apply | Check current settings | Home Grown Territory Grant available for new homes |
A general guide only. Thresholds and dates change with state budgets. Use your state revenue office calculator and ask your conveyancer to confirm.
Generally, you and anyone buying with you must never have owned residential property in Australia, buy as an individual (not a company or trust), be buying a home or eligible land in that state, intend to live in it as your main residence, and meet any value caps and citizenship or residency rules. If one buyer isn't a first home buyer, you may lose the concession or only get part of it. Adding parents to the title to help with borrowing can also affect eligibility. A guarantor doesn't need to be on the title.
Most exemptions and concessions require you to move in within a set time, often 12 months, and live there continuously for a minimum period, often 6 or 12 months. If you don't, for example by renting the property out straight away, you may lose the concession and have to repay it, possibly with interest or penalties. Revenue offices can check by asking for utility bills, license and electoral roll details, insurance documents or tenancy records. If your plans change because of work, family or construction delays, talk to your conveyancer early.
Ask your conveyancer to confirm your concession based on the actual contract, the names on title and your occupancy plans.
Confirm likely eligibility based on who will be on title, the property type, the price and your plans to live there.
Make sure the contract matches the scenario you're claiming, especially for off-the-plan and new builds.
Sign the first home buyer and occupancy declarations.
The concession or exemption is applied in the duty assessment.
Duty is paid, reduced or waived.
Move in and live there as required, and keep evidence.
Yes. Many states officially call it transfer duty or conveyance duty.
No. It's set by each state and territory, so the rules vary.
No. Some get a full exemption, some a partial concession, and some nothing if they're over the caps or don't meet the rules.
Yes, unless you qualify for an exemption or concession. Your deposit size doesn't change the duty.
Usually no. First home buyer concessions generally require you to live in the home.
In some states, yes, with their own value caps and building deadlines.
No. They're separate programs. You may qualify for both, one or neither.
Often your concession is reduced or removed, depending on the state.
Many schemes only look at property owned in Australia, but other rules may apply. Check your state's rules.
Yes, if you don't meet the conditions, especially the residence rule. The revenue office can reassess the duty.
Sometimes, if you genuinely live there as your main home, but it depends on the state.
Conveyancing, building and pest inspections, strata reports, loan and valuation fees, registration fees and moving costs.
Tell us where you're buying and we'll estimate your stamp duty and total upfront costs. We'll be in touch within one business day.



Kubaer Finance helps working families and migrants in Adelaide secure home, car, and investment loans with personalised guidance.