
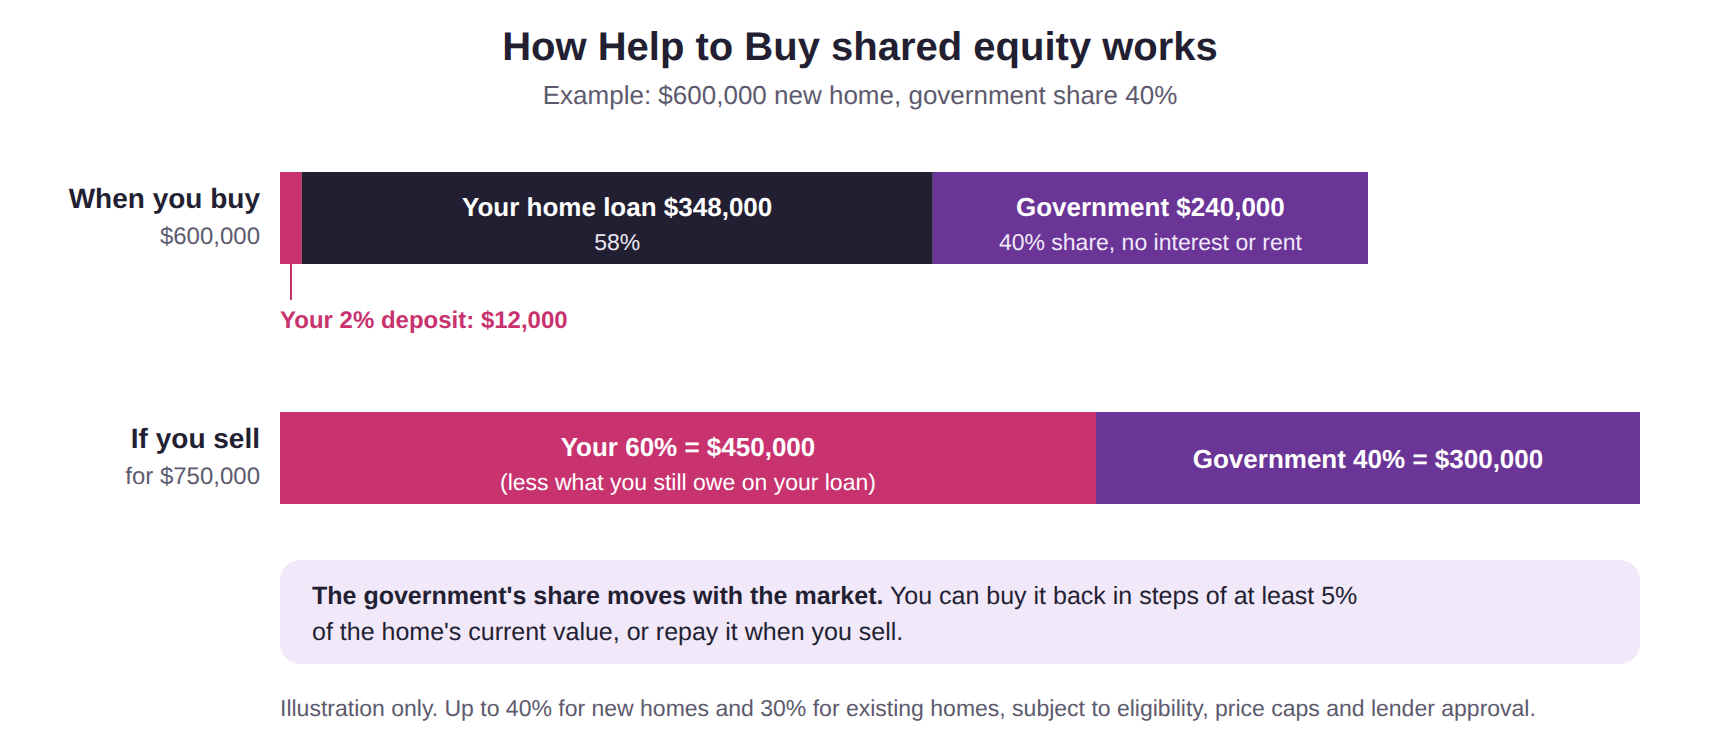
The Government Shares the Cost of Your Home. Help to Buy is an Australian Government shared equity scheme that lets eligible buyers purchase with as little as a 2% deposit. The government contributes up to 40% of the price of a new home, or up to 30% of an existing home, in return for an equal share of the property, so you borrow much less.
Your name is on the title and you live in the home as the owner. The government holds an equity share that rises or falls with the property's value. You don't pay interest or rent on the government's share and don't make repayments on it while you live there. You can buy back the government's share over time in steps of at least 5% of the home's current value, or all at once. When you sell, the government receives its percentage of the sale price, so it shares in any gain or loss.
You must be an Australian citizen aged 18 or over, buying alone or with one other person, and the home must be your principal place of residence. You can't own any property in Australia or overseas, although single parents have some exceptions. Your deposit must be at least 2% of the price, and you must contribute the largest deposit you reasonably can. Income limits apply and are indexed each 1 July. For 2026–27, your taxable income must be $103,000 or less as an individual, or $165,000 or less for joint applicants and single parents, based on your latest Notice of Assessment. You can't use other Australian Government shared equity schemes, guarantees or loans for the same purchase, but you can use state grants and stamp duty concessions.
You’ll still pay stamp duty (unless you qualify for a concession), legal and conveyancing fees, inspections, mortgage registration (including for the government’s share) and home insurance, which is compulsory under the scheme.
Each buy-back must be at least 5% of the home's current value, rounded to the nearest $1,000, and is priced at today's value, not the original contribution. For example, if your home bought for $800,000 is now worth $880,000, buying back 5% costs $44,000. If your income goes over the scheme limits for two consecutive years, you may be required to buy back some or all of the government's share. Housing Australia will work with you to find an affordable way, often by refinancing with your participating lender.
Your building contract must be with a licensed builder who isn't related to you, cover the whole build at a fixed price within the price cap, and include the required insurance. Construction must start within 12 months of owning the land and finish within 36 months, and the land must settle within 90 days of approval. If costs rise, you or your lender must cover the increase where possible, and the government's contribution can't go above 40%. Keeping a buffer of around 5% of the build cost from your savings is a sensible safety net.
Help to Buy can cut your repayments a lot, but the government shares in any rise in value. If you expect your income to grow fast, compare it carefully with the 5% Deposit Scheme.
Citizenship, income, deposit, property ownership and the price cap for your area.
We'll confirm whether Help to Buy or another scheme suits you, and connect you with a participating lender.
The lender submits your application to Housing Australia, which reserves your place for 90 days (extensions may be possible).
Get legal advice, allow at least 30 days between signing and settlement, tell your lender, and arrange home insurance.
Sign the participation agreement and mortgage documents, and settle.
| Feature ($600,000 existing home) | Help to Buy | First Home Guarantee |
|---|---|---|
| Minimum deposit | $12,000 (2%) | $30,000 (5%) |
| Government support | $180,000 equity share (30%) | Guarantee of 15% (~$90,000) |
| Loan amount | $408,000 | $570,000 |
| Monthly repayments (30 years, 6% p.a.) | $2,446 | $3,417 |
| Total interest over 30 years | $472,620 | $660,278 |
| Your equity after 5 years if the home is worth $750,000 | 19.38% ($145,338) | 29.28% ($219,590) |
Illustration only; assumes 6.00% p.a. for 30 years and excludes fees. Help to Buy equity excludes the government’s 30% share, which you must eventually buy back.
| Region | Price cap | Max government share, new home (40%) | Max government share, existing home (30%) |
|---|---|---|---|
| NSW: Sydney and regional centres | $1,300,000 | $520,000 | $390,000 |
| NSW: rest of state | $800,000 | $320,000 | $240,000 |
| VIC: Melbourne and Geelong | $950,000 | $380,000 | $285,000 |
| VIC: rest of state | $650,000 | $260,000 | $195,000 |
| QLD: Brisbane, Gold Coast, Sunshine Coast | $1,000,000 | $400,000 | $300,000 |
| QLD: rest of state | $700,000 | $280,000 | $210,000 |
| WA: Perth | $850,000 | $340,000 | $255,000 |
| WA: rest of state | $600,000 | $240,000 | $180,000 |
| SA: Adelaide | $900,000 | $360,000 | $270,000 |
| SA: rest of state | $500,000 | $200,000 | $150,000 |
| TAS: Hobart | $700,000 | $280,000 | $210,000 |
| TAS: rest of state | $550,000 | $220,000 | $165,000 |
| ACT | $1,000,000 | $400,000 | $300,000 |
| NT | $600,000 | $240,000 | $180,000 |
Confirm the cap for your postcode with the Help to Buy postcode lookup tool on firsthomebuyers.gov.au.
Minor work that doesn't need council approval is fine. Bigger renovations need Housing Australia's involvement, with valuations before and after so the value added is shared fairly.
No. It's open to eligible buyers who don't own any property when they apply.
No. It's an equity investment by the government. You repay its share when you sell, voluntarily over time, or if your income rises above the limits.
No. Repayments are based on the share's current market value when you buy it back.
Yes, at any time. The government receives its percentage of the sale price.
Yes. You can use state grants and stamp duty concessions, but not the 5% Deposit Scheme or other Australian Government guarantees or loans.
Yes. You can refinance with a participating lender to buy back part or all of the share (minimum 5%). If you move to a non-participating lender, you must buy back the share in full.
No. Your lender still assesses whether you can afford the repayments.
Only a small number of participating lenders so far, including Commonwealth Bank and Bank Australia, with more joining. We'll tell you which ones suit you.
Tell us about your situation and we'll be in touch within one business day. There's no obligation and no cost for an initial chat.



Kubaer Finance helps working families and migrants in Adelaide secure home, car, and investment loans with personalised guidance.